Correction, October 29, 2026: This March 19 article previously made unsupported claims about RBI's brands and attributed interviews to named and unnamed sources that we could not substantiate in the available reporting records. Those quotations and the associated judgments have been removed. The earlier headline also confused corporate and restaurant profitability, and the Carrols acquisition account misstated its circumstances and restaurant count. We have replaced the article with the documented account below, using records available before its original publication date. The original date is retained; this notice identifies when the correction was made. We regret the errors.
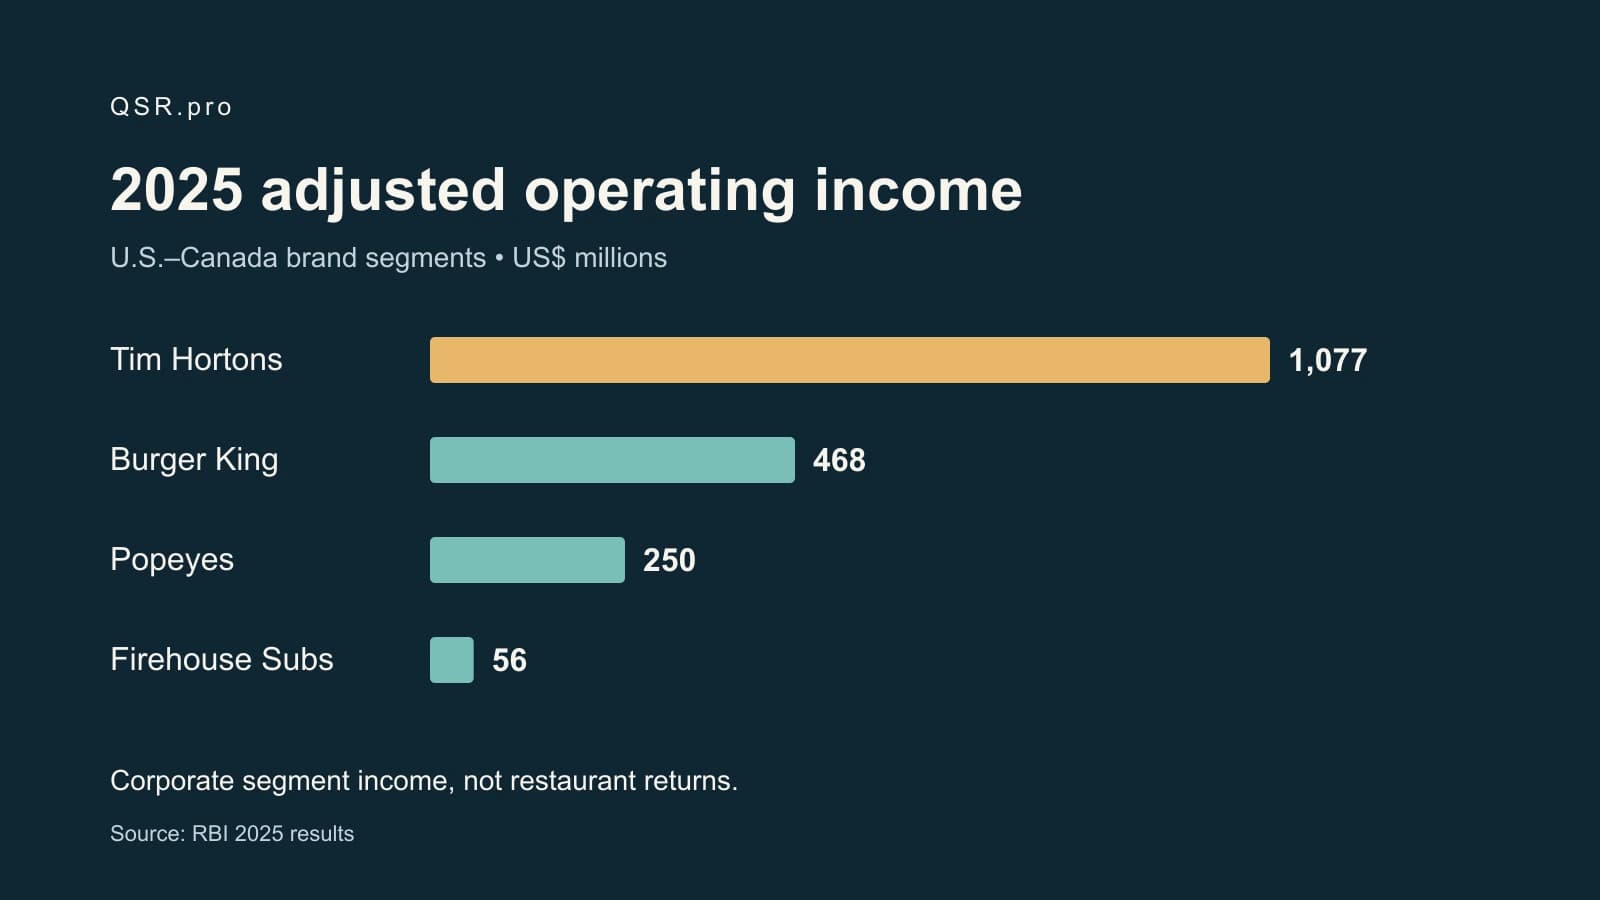
Restaurant Brands International reported positive adjusted operating income for the year ended December 31, 2025, in each of its four U.S.–Canada brand segments: Tim Hortons, $1.077 billion; Burger King, $468 million; and Popeyes, $250 million, and Firehouse Subs, $56 million. All amounts are in U.S. dollars.
RBI defines this non-GAAP measure as corporate segment income with specified exclusions, including amortization of acquired franchise rights and certain transaction costs. These adjustments mean it differs from GAAP operating income. It does not establish the return on an individual restaurant investment. International operations and Restaurant Holdings have separate reporting segments.
What the parent earns#
The 2025 annual filing says royalties for standard U.S. and Canadian restaurants typically range from 3% to 6% of gross sales. Nonstandard agreements and incentives can change those terms. Since the base is sales, royalties can remain payable when a restaurant's costs leave little income.
RBI's revenue categories include rent from properties leased or subleased to franchisees, company restaurant sales and a supply business. Tim Hortons' global supply-chain sales sit in the TH segment, including products, supplies and equipment resold to franchisees. The filing lists food, wages and occupancy among company restaurant expenses, distinguishing the costs of operating restaurants from collecting franchise fees.
Carrols illustrates that split. RBI reports the acquired Burger King restaurants' operating results in Restaurant Holdings. Their royalties and rent appear as revenue in the Burger King segment and are eliminated when RBI combines its accounts. A single acquired restaurant therefore contributes to both segment presentations, without generating two sets of sales to outside customers.
What happened at Carrols#
RBI completed its Carrols purchase on May 16, 2024. It paid $9.55 in cash for each outstanding share it or its affiliates did not already own; the announcement put the enterprise value at approximately $1 billion. Carrols then operated 1,023 Burger King restaurants and 59 Popeyes restaurants. Those are the closing-date counts, not a description of today's portfolio.
The announcement set out a further $500 million investment to reimage more than 600 Carrols restaurants and a plan to refranchise the majority to new or existing smaller operators over seven years. Those were the plans at closing. The acquisition was financed with cash on hand and an increase in RBI subsidiaries' term loan facility, which also funded repayment of Carrols' debt. The roughly $1 billion enterprise value described the transaction; the further $500 million described planned restaurant investment. Neither figure was a purchase price for an individual location.
QSR Pro Staff
The QSR Pro editorial team covers the quick service restaurant industry with in-depth analysis, data-driven reporting, and operator-first perspective.
More from QSR