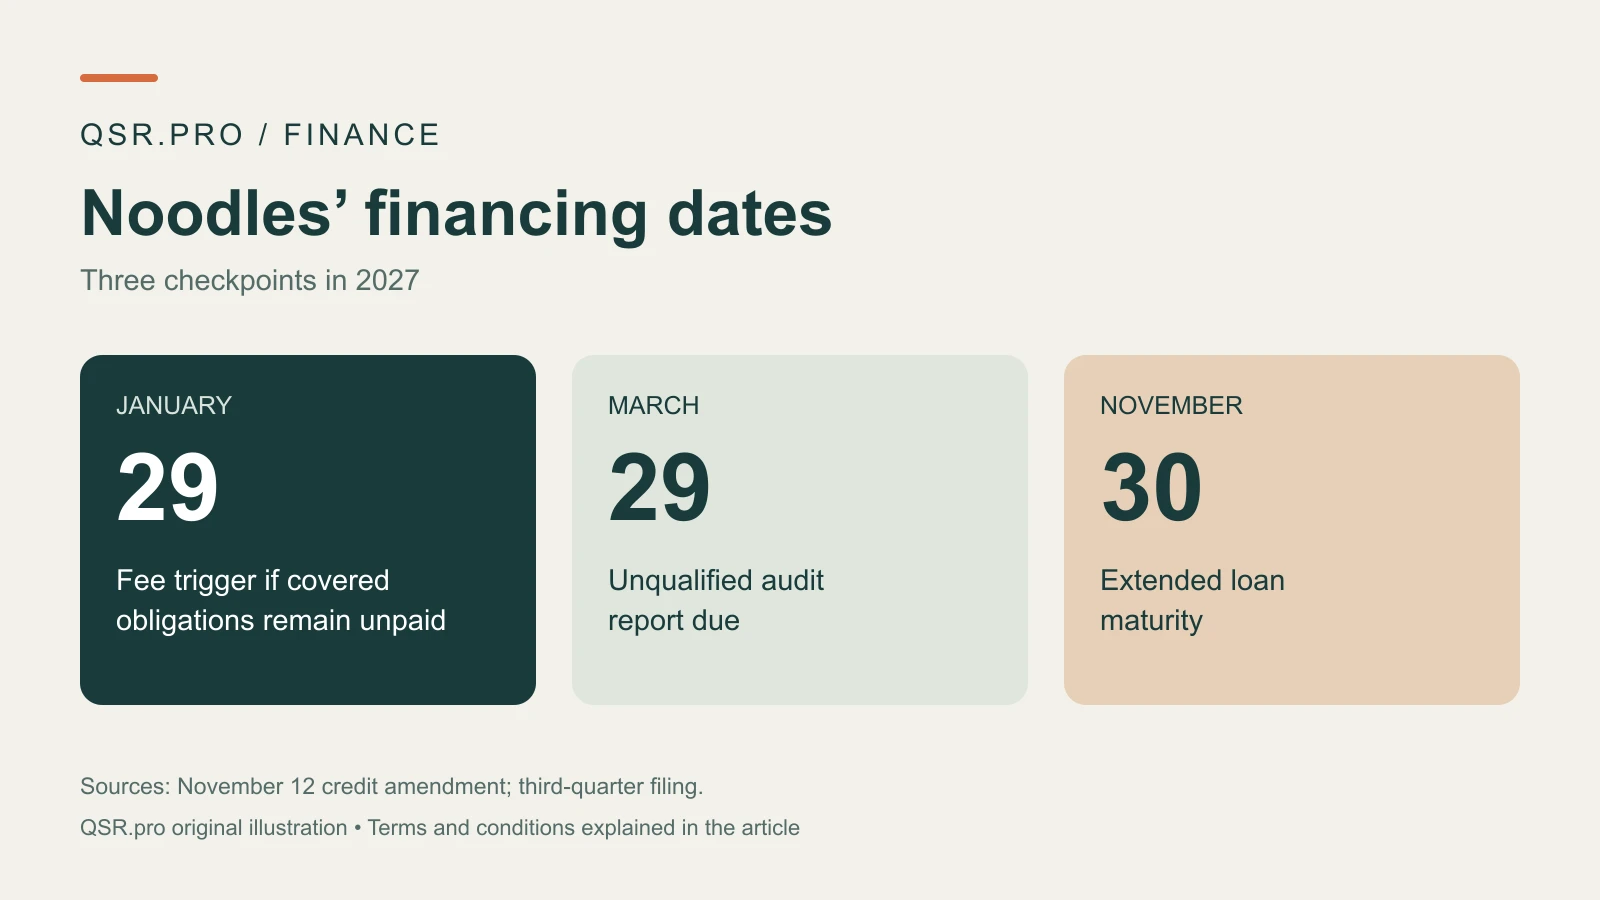
Noodles & Company extended its credit facility’s maturity to November 30, 2027, in a November 12 amendment announced with its November 13 results.
The signed agreement requires a $750,000 extension fee. Unless covered obligations are fully paid in cash by January 29, 2027, a $1.25 million fee is due the next business day to lenders through agent U.S. Bank. From January 30, all loans then carry the Secured Overnight Financing Rate (SOFR) plus 7%. A 3% SOFR floor means at least 10%. Through January 29, SOFR loans carry a 3.25% margin. The payoff test excludes unasserted contingent obligations.
Existing bank letters of credit will not renew. Noodles must post 105% of their stated value in cash by January 29, or upon earlier full cash repayment of all revolving loans. Third-party replacements are permitted. Collateral is released after expiry and documented cancellation, less amounts still owed. Collateral terms
Those guarantees support workers’ compensation and certain leases. They totaled $2.8 million at September 29, 2026, according to the quarterly filing. That balance does not establish January’s collateral requirement.
Credit also funds restaurant investment#
The facility was reduced to $120 million; its previous maturity was July 27, 2027. Noodles uses cash and revolving credit for restaurant reinvestment, technology and working capital. The company says its strategic review is primarily focused on refinancing. Liquidity and financing plans
An unqualified auditor’s report for fiscal 2026 is required by March 29, 2027. Noodles warns that without new financing, capital or a lender agreement by then, it could breach that covenant. Without a waiver, noncompliance could stop further borrowing and let lenders accelerate repayment. Noodles reported compliance at September 29 and expects to remain compliant for 12 months after its November 13 report. Audit covenant
At that quarter-end, Noodles reported $1.5 million cash, $101 million debt and $21.2 million available revolving borrowings. Those balances precede the amendment and do not measure capacity under the revised terms. Quarter-end liquidity
The company’s 2026 outlook calls for $8.5 million–$9.5 million in capital spending, 34–36 company-restaurant closures and 7–8 franchise closures. It reported a $2.1 million third-quarter net loss, compared with $9.2 million a year earlier. Company-restaurant comparable sales rose 10.7%; franchise comparable sales increased 4.9%. Results and outlook
QSR Pro Staff
The QSR Pro editorial team covers the quick service restaurant industry with in-depth analysis, data-driven reporting, and operator-first perspective.
More from QSR